

I've been carrying the Chase Sapphire Reserve since 2017, and the 2025 redesign is the first time I've had to genuinely re-do my own math on it. The annual fee jumped from $550 to $795. The earning structure flattened on direct travel and bumped on Chase Travel. The credits changed too. So the real question in 2026 isn't "is the Reserve worth it?", it's "is the Reserve still the Reserve after Chase rebuilt it?"
Short answer: yes, for a smaller group of people than before. If you're booking through Chase Travel a few times a year, using the lounges, and actually pulling the new credits, the $795 fee still pencils out. If you were using it as a 3x dining card with airport lounge access on the side, the Chase Sapphire Preferred is now the smarter buy. Let me walk through the math.
Quick Summary
Best For: Travelers who book through Chase Travel, use Priority Pass, and will actually use the DoorDash promos and the Lyft and StubHub credits. Standout Benefit: 8x Ultimate Rewards on Chase Travel bookings. Biggest Drawback: $795 annual fee with credits that require monthly attention to fully capture. Current Offer: 100,000 bonus points after $6,000 in purchases in the first 3 months.
Apply for the Chase Sapphire Reserve
What Actually Changed in the 2025 Refresh
For context: Chase rebuilt the Reserve in mid-2025. Here's what's different in 2026 versus the version most existing reviews still describe.
The fee moved from $550 to $795.
The earning structure changed. The old card earned 10x on hotels and cars through Chase Travel, 5x on flights through Chase Travel, and 3x on all other travel and dining. The 2026 card earns 8x on all Chase Travel bookings (flights, hotels, cars), 4x on flights and hotels booked directly with the airline or hotel, and 3x on dining worldwide. Lower ceiling on portal hotels, higher floor on direct bookings.
The credits got rebuilt. The 2026 card's bundle includes a DashPass membership and monthly DoorDash promos, StubHub credits, Apple TV and Apple Music subscriptions, Lyft credits and Peloton credits. The $300 annual travel credit stayed. The $120 Global Entry or TSA PreCheck credit (refreshed every four years) stayed.
Priority Pass and Chase Sapphire Lounge access stayed. The travel insurance package stayed. The transfer partners stayed.
Net effect: more annual fee, more credit value if you use it, less raw earning on the old portal categories, and a card that's now firmly in the same fee tier as the Amex Platinum. Which is the right comparison to make and we'll get there.
How the New Earning Structure Plays Out
The 8x on Chase Travel bookings is the headline rate, and it's the simplest place to start. Say you book a $1,000 hotel stay through Chase Travel: that earns 8,000 Ultimate Rewards points. If you transfer them to Hyatt and get 2 cents per point, that's $160 of value back on the stay.
The 4x on direct bookings is the change most existing Reserve holders feel. If you're booking Hyatt direct (because you want elite night credit toward Globalist), or Hilton direct, or buying a flight straight from United's website, you're earning 4x instead of the old 3x. That's actually a small win for direct bookers, who got penalized on the old card.
The 3x on dining worldwide is the Reserve's only bonus rate outside travel, and everything else earns 1x. So if dining is the only reason you're considering the Reserve, the Sapphire Preferred is the right card. I say this every time someone asks me about the Reserve and someone always ignores it.
Say you spend $4,000 a year on Chase Travel hotels, $3,000 on flights booked direct, $6,000 on dining and $7,000 on everything else. That earns 32,000 + 12,000 + 18,000 + 7,000 = 69,000 points a year, and at 2 cents a point that's $1,380 in points value. That's before the 100,000-point welcome bonus and before any credits.
The Credit Stack and What It's Actually Worth
The $795 fee feels different once you start subtracting credits. The trick is: you have to use them, and Chase made some of them deliberately fiddly.
$300 annual travel credit. Up to $300 in statement credits for travel purchases each account anniversary year, applied automatically. Purchases that get the credit don't earn points. This is the easiest $300 in the credit card industry. If you travel at all, you'll trigger it without thinking.
The Edit credit. Up to $250 in statement credits for each prepaid "Pay Now" booking of two nights or more with The Edit by Chase Travel, up to $500 each calendar year, starting January 1, 2026. Purchases that get the credit don't earn points.
Select hotels credit, 2026 only. Up to $250 in statement credits from January 1 through December 31, 2026 on prepaid Chase Travel stays of two nights or more at IHG Hotels & Resorts, Montage, Pendry, Omni, Virgin Hotels, Minor Hotels and Pan Pacific. Purchases that get the credit don't earn points.
Dining credit. Up to $150 in statement credits from January through June and again from July through December when you dine at restaurants in the Sapphire Reserve Exclusive Tables program on OpenTable.
DoorDash promos. From October 1, 2026, through the end of 2029, Chase gives Reserve cardmembers up to $35 a month to spend on DoorDash: a $15 monthly promo on any qualifying DoorDash order and two $10 monthly promos for groceries, daily essentials and more. The promos start once you activate the complimentary DashPass membership with your Reserve card, which you need to do by December 31, 2029. It's worth it if you're a regular DoorDash user. Zero if you don't order delivery.
StubHub credit. Up to $150 in statement credits from January through June and again from July through December, for a maximum of $300 a year, on StubHub and viagogo purchases through December 31, 2027. Activation required. Useful if you go to live events. If you'd buy concert or sports tickets anyway, it's effectively cash. If you wouldn't, it's worth what you'd pay for tickets you don't actually want, which is zero.
Apple TV and Apple Music subscriptions. Chase's benefits page values them at $324 a year, and the subscriptions run through June 22, 2027. One-time activation is required. That value is real only if you'd pay for both anyway.
$120 Global Entry, TSA PreCheck or NEXUS credit, every four years. One statement credit of up to $120 every four years as reimbursement for the application fee charged to your card.
Lyft credit. Up to $10 a month in in-app Lyft ride credits through September 30, 2027, plus 5x total points on Lyft rides through the same date.
Peloton credit. Up to $10 a month in statement credits on eligible Peloton memberships through December 31, 2027. Activation required.
The Reserve's credit math has gotten more like the Amex Platinum's over the past two refreshes. There's a lot of nominal credit value if you use everything. There's also enough fragmentation that it's easy to capture only part of it. Be honest with yourself about which group you're in before you apply.
Lounge Access Is Still the Hidden Reason People Get This Card
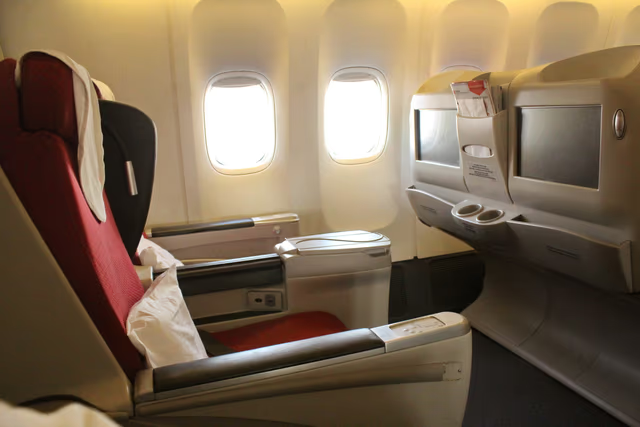
Priority Pass Select, with up to two guests, is still on the card, and it's still one of the best in the industry. Chase Sapphire Lounges by The Club are in the wallet too. Chase values the lounge access at over $850 when you and your guests visit multiple times each year, and that's money you'd otherwise spend on overpriced airport meals.
I've stopped trying to formally line-item lounge value in my CSR math because the real benefit is qualitative: showers in San Francisco, a shockingly good lunch in Hong Kong, somewhere quiet to work between flights. If you don't travel through hubs with Priority Pass coverage, this benefit is worth zero to you. If you do, it's the single best reason to hold the card.
Travel Insurance: The Part Nobody Reads Until They Need It
The Reserve still has the strongest travel protection package in its tier. Trip cancellation and interruption coverage up to $10,000 per covered traveler and $20,000 per trip. Trip delay coverage up to $500 per covered traveler. Primary rental car insurance, which is the one I actually care about: it covers the rental directly without going through your personal auto insurance first, which is what saves you from a premium hike after a parking lot fender bender. Chase's Guide to Benefits makes one exception: for New York residents renting inside the United States, the coverage is primary unless they have personal auto insurance, in which case it's excess. Lost baggage, baggage delay, emergency evacuation. The full stack.
Last year, our flight to Buenos Aires got delayed long enough to trigger trip delay coverage. Chase reimbursed our hotel and dinner without making me prove anything beyond submitting receipts and the original itinerary. That experience is part of why I keep paying the fee.
How the Reserve Compares Now
Versus Sapphire Preferred. $95 vs $795 fee. The Preferred earns 5x on Chase Travel and 3x on dining. The Reserve earns 8x on Chase Travel and 3x on dining. If the only thing you'd use is the dining rate and occasional Chase Travel booking, the Preferred captures most of the value for a $95 fee. The Reserve makes sense once you're using lounges and the credit stack regularly. If you're not, downgrade.
Versus Capital One Venture X. $395 vs $795 fee. Venture X earns 10x on Capital One Travel hotels, 5x on flights through their portal, 2x everywhere else, with a $300 Capital One Travel credit and Priority Pass. It's a cheaper card with comparable lounge benefits. The deciding factor is the transfer partners. Chase has Hyatt and United, which I value at over 2 cents per point in practice. Capital One has Air Canada, Turkish, and Avianca, which are excellent for international business class but require more legwork. If your redemption strategy is "Hyatt and United," stay with the Reserve. If it's "international award flights through whichever program has space," the Venture X is the better dollar.
Versus Amex Platinum. $895 vs $795 fee, after Amex raised the Platinum's fee in 2025 and Chase raised the Reserve's. The Platinum has Centurion Lounges, which beat Priority Pass on average, and Fine Hotels & Resorts, which gives you fourth night free and elite-style perks at hundreds of luxury properties. The Reserve has stronger transfer partners for most domestic flyers (Hyatt, United, Southwest) and a more flexible $300 travel credit versus the Platinum's airline-and-hotel-specific credits. I hold both, which I know is excessive, but if forced to pick one, I'd take the Reserve for the transfer partners and the Platinum for the lounge network. They serve different jobs.
Who Should Get the Reserve in 2026
You should get this card if:
- You'll book through Chase Travel at least twice a year and you'll fly enough to use Priority Pass on three or more trips.
- You're already a DoorDash regular, an Apple subscriber, or a frequent Lyft user, so those promos, subscriptions and credits turn into actual money instead of theoretical value.
- You want the strongest travel insurance in the premium tier and the primary rental car coverage matters to you.
- You're already in the Chase Ultimate Rewards ecosystem with a Freedom Unlimited or Freedom Flex, so the Reserve becomes the hub that converts your Freedom-card earning into transferable points worth 2 cents apiece.
This isn't the right card if you're a light traveler taking one or two trips a year. The Sapphire Preferred earns the same 3x on dining at a $95 fee and gets you into the same transfer-partner ecosystem. If grocery and gas are the bulk of your spend, you're better off with the Amex Gold or a flat-rate cash-back card paired with a Sapphire Preferred for travel. And if monthly credits stress you out, the credit stack on this card will not stop stressing you out. Pick the Venture X, which front-loads its credit into one $300 annual travel block.
A Note on the 5/24 Rule
Chase's 5/24 rule still applies to the Reserve. If you've opened five or more credit cards from any issuer in the past 24 months, Chase will deny the application regardless of credit score. This trips up a lot of points-game beginners who churn through several cards in a year and then get blocked from the Reserve. If you're at four-of-twenty-four and considering the Reserve, get it before you open another card. Chase's page also says the card is unavailable if you currently have it open, and the new cardmember bonus may not be available if you previously held the card or received its bonus.
If you're approved and decide later the fee isn't justified, you can product-change to the Sapphire Preferred or downgrade to a no-fee Freedom card after year one. Your Ultimate Rewards points come with you. This is the safety valve that makes applying lower-risk than it sounds.
Final Verdict
The Chase Sapphire Reserve at $795 is a narrower card than it was at $550. The math still works, but it works for a more specific traveler: someone who books through Chase Travel, flies enough to use the lounges, and treats the new credit stack as a series of real monthly tasks rather than vague nice-to-haves. For that person, this is still one of the two or three best premium travel cards in the U.S. market.
For everyone else, the Sapphire Preferred at $95 is the answer, and it's not close. Same transfer partners, same dining rate, and a $95 annual fee. The Reserve earns its keep through travel benefits, not earning rates. Check the current offer here and run your own numbers before you apply.
For other angles on the same card, see our 2026 verdict on the $795 fee and our look at which traveler it pays back.
Updated October 6, 2026: related articles.